Lovable grew out of an open-source coding experiment and became a platform for building software through natural language. Its larger commercial opportunity may have come not only from making developers faster, but from letting founders, designers, salespeople and other non-specialists build working applications, while progressively absorbing more of the backend, deployment and infrastructure required to make those applications usable.
Lovable’s growth story is easy to flatten into a familiar AI narrative. An open-source coding project attracted attention. A commercial product followed. Vibe coding became a recognizable category. Revenue rose quickly. Investors assigned the company increasingly large valuations. That version is not wrong so much as incomplete.
Lovable did begin with an open-source project called gpt-engineer. The company later built a commercial web product and eventually relaunched the idea as Lovable. By July 2025, the company said it had reached $100 million in annual recurring revenue. By November, it reported $200 million in ARR. Then the financial language changed. In early 2026, Lovable said it had surpassed $400 million in annualized revenue. By June, the company told TechCrunch that it had crossed a $500 million annualized revenue run rate. Those are remarkable private-company claims, but they should not be compressed into a single audited ARR curve. ARR, annualized revenue and annualized revenue run rate are not automatically interchangeable, and none of those metrics should be confused with recognized annual revenue or profit.
The more interesting question is what Lovable was actually selling as the business expanded. At first glance, the answer appears simple: AI that writes code. But the product increasingly encompassed more of what sits around code: interface generation, backend services, authentication, storage, deployment, AI capabilities, integrations and enterprise workflows.
The user changed too. Lovable’s materials and third-party reporting describe founders, designers, salespeople and other non-technical users alongside professional developers. That does not mean developers became unnecessary. Lovable’s own enterprise guidance still describes workflows in which non-technical teams prototype and engineering teams review or take over production systems.
The broader shift may be more subtle. Lovable appears to be reducing the amount of specialized technical work required between an idea and a usable application. That creates a larger potential builder base. It also creates a harder second question. Making software easier to create does not automatically make it easier to maintain, secure or govern over time.
Quick Snapshot
| Business | Lovable |
| Founders | Anton Osika / Fabian Hedin |
| Founded | Late 2023 |
| Public Product Launch | November 2024 |
| Category | AI Software Creation / Vibe Coding / Application Development Platform |
| Historical Origin | Open-source gpt-engineer project launched in mid-2023 |
| Early Commercialization | Commercial web product followed the open-source project; Lovable later described its first two commercial launches as failing to gain meaningful traction |
| Core Product Shift | Terminal-oriented AI coding experiment to natural-language commercial application builder |
| Important User Expansion | Founders, designers, salespeople and other non-technical users appear alongside professional developers in company and third-party reporting |
| Jan. 2025 Revenue Claim | $10M ARR – company-reported |
| Feb. 2025 Revenue Claim | $17M ARR – company-reported via TechCrunch |
| Jul. 2025 Revenue Claim | $100M ARR – company-reported + strong third-party corroboration, not independently audited |
| Nov. 2025 Revenue Claim | $200M ARR – company-reported + third-party corroboration, not independently audited |
| Feb. 2026 Revenue Claim | More than $400M annualized revenue – company-reported via third-party reporting |
| Jun. 2026 Revenue Claim | More than $500M annualized revenue run rate – company-reported via third-party reporting |
| Aug. 2026 Project Scale | ~60M projects – company-reported |
| Hosted Project Traffic | ~900M monthly visitors to hosted projects – company-reported via third-party reporting |
| Revenue Architecture | Self-serve subscriptions / credits / cloud and AI usage / enterprise offerings |
| AI Architecture | External frontier models + model routing/orchestration + company-reported post-trained internal models |
| Series A | $200M / $1.8B valuation – July 2025 |
| Series B | $330M / $6.6B valuation – December 2025 |
| Series C | $400M / $13.3B valuation – August 2026 |
| Security / Maintenance Context | Fast creation does not establish long-term maintainability, governance or security; Lovable disclosed a public-project access incident in April 2026 |
| Verification | Private-company revenue, project and user metrics are not treated as independently audited unless explicitly established |
The Short Version
Lovable began with gpt-engineer, an open-source AI coding project launched in 2023.
The early product was closer to a developer-oriented experiment than the polished commercial platform Lovable later became. The team subsequently built a web-based version and tried to commercialize the technology. That transition was not immediately successful. Lovable later described its first two commercial launches as failing to gain meaningful traction. In the company’s own retrospective, product positioning, user validation and distribution all needed work.
The eventual product changed more than its branding. Natural language became a primary interface to software creation, allowing users to describe what they wanted rather than manually implement every component themselves. That broadened the potential audience: company material and third-party reporting describe founders, designers, salespeople and other non-specialists building applications alongside developers.
But software creation does not end when code appears on a screen. Applications need databases, authentication, storage, APIs, deployment, runtime infrastructure and, eventually, maintenance. Lovable increasingly moved those layers into the product as well. Integrations, GitHub workflows, visual editing, agent capabilities and later Lovable Cloud pushed the company toward a broader application-development platform. At the same time, reported revenue rose extraordinarily quickly.
Lovable said it reached $10 million in ARR in early 2025, $17 million in February, $100 million in July and $200 million in November.
The terminology then changed. In 2026, the company reported more than $400 million in annualized revenue and later more than $500 million in annualized revenue run rate.
RevenueLore does not treat those later figures as audited ARR.
The company has also reported tens of millions of projects and enormous traffic to applications built on its platform. Those figures demonstrate reported activity at scale, but projects are not the same as customers, active production applications or durable businesses.
The bigger commercial question may therefore extend beyond coding.
If Lovable makes custom software cheaper and easier to create, organizations may reconsider when they should buy existing SaaS and when they should build something themselves.
But lower creation cost does not eliminate the cost of maintenance, security or governance.
Lovable’s first challenge was proving that more people could build software.
Its longer-term challenge may be proving that software built by more people can remain reliable enough to operate.
1. Lovable Started as an Open-Source Coding Experiment
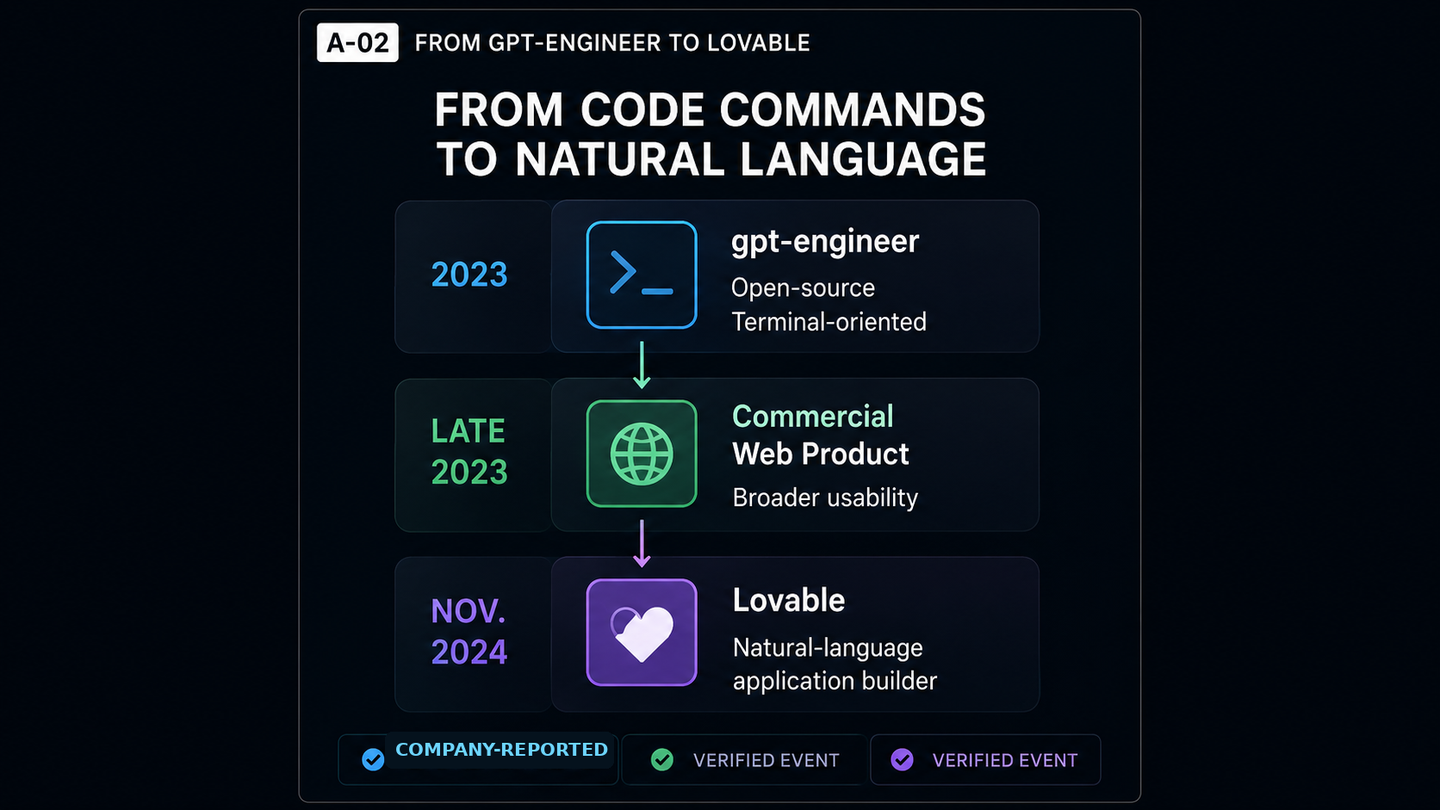
Lovable did not begin as a conventional SaaS company with a polished dashboard, pricing page and enterprise sales organization. Its roots were in gpt-engineer, an open-source project launched in 2023. The early concept was straightforward: let a user describe what they wanted to build and use AI to help generate the corresponding software.
The original environment was comparatively technical. It was oriented toward people comfortable working from a terminal and interacting with code. That made it a useful experiment in AI-assisted software creation, but it was not yet the same product that Lovable would later sell to a broader market. The team eventually created a commercial web version, gptengineer.app, with the goal of making the same underlying idea accessible to people who were not necessarily professional developers. Lovable was founded later in 2023, and the product that would carry the Lovable name formally launched in November 2024.
The historical progression matters. The company did not begin by discovering a finished mass-market category. It began with a technical experiment and gradually changed who could use it and what the product needed to provide.
2. Open-Source Attention Was Not the Same as a Business
The open-source project attracted substantial attention. Lovable has described gpt-engineer as one of the fastest-growing repositories on GitHub and continues to present it as an important part of the company’s origin story. That attention was valuable. It demonstrated interest in the idea of instructing AI to build software from natural-language requirements.
But open-source adoption and commercial demand are different things. A developer can star a repository, test it, fork it or experiment with it without becoming a paying customer. Open-source popularity also does not determine which product packaging, pricing model or user segment will produce a repeatable business.
That distinction became visible as the team attempted to commercialize the idea. The technology had attention. The company still had to discover how to turn that attention into a product people would reliably pay for.
3. The First Commercial Launches Did Not Immediately Work
Lovable has been unusually direct about the fact that commercialization did not work immediately. In a later retrospective, the company described its first two commercial launches as failed launches. That wording needs context.
It does not mean that gpt-engineer failed technically or that nobody wanted AI-assisted software creation. The company’s own explanation focuses instead on product positioning, user validation and distribution. One problem was perception. Lovable said the earlier GPT Engineer identity could be interpreted more as an interesting AI toy than as a serious product for building useful software. The team also concluded that it needed a stronger understanding of what users actually wanted from the product.
Those lessons influenced the next launch. The commercial story therefore did not begin with a perfect product immediately finding product-market fit. It included failed attempts to package and position an already-interesting technical capability.
4. The Breakthrough Was Not One Growth Hack
It would be convenient to identify one distribution channel that created Lovable’s growth.
The public record does not support that conclusion.
Lovable has described a mixture of activities around its later launch: Product Hunt, community engagement, social platforms, user-generated content, influencer outreach, partnerships and integrations.
TechCrunch separately reported that the product gained exposure on Product Hunt and Hacker News.
Supabase and other integrations also became part of the product and marketing story.
Any of those may have contributed.
The evidence does not establish that one of them independently caused the later growth.
This matters because rapidly growing software companies are often reduced to a single growth tactic after the fact.
In reality, product changes, distribution, brand positioning, integrations and market timing can move together.
Lovable’s own retrospective suggests exactly that kind of overlap.
The company did not describe a single marketing switch.
It described an iterative commercial system.
5. Lovable Changed the Interface to Software Creation
The most obvious product change was the interface.
Traditional software development requires a user to express an idea in forms computers can execute: programming languages, frameworks, configuration files, database schemas and deployment systems.
Lovable moved more of that translation into the product.
A user could describe what they wanted in natural language and let the system generate much of the application structure.
That does not remove software engineering from the process.
It changes where some of the technical translation happens.
The user increasingly communicates intent rather than manually specifying every implementation detail.
For an experienced developer, that can mean acceleration.
For someone who cannot code, it can mean access to a workflow that was previously unavailable.
That difference is commercially important.
A product that makes existing developers 20% or 50% faster competes inside the existing developer-tools market.
A product that allows new categories of people to participate in software creation may expand the potential market itself.
6. The Potential User Was No Longer Only a Developer
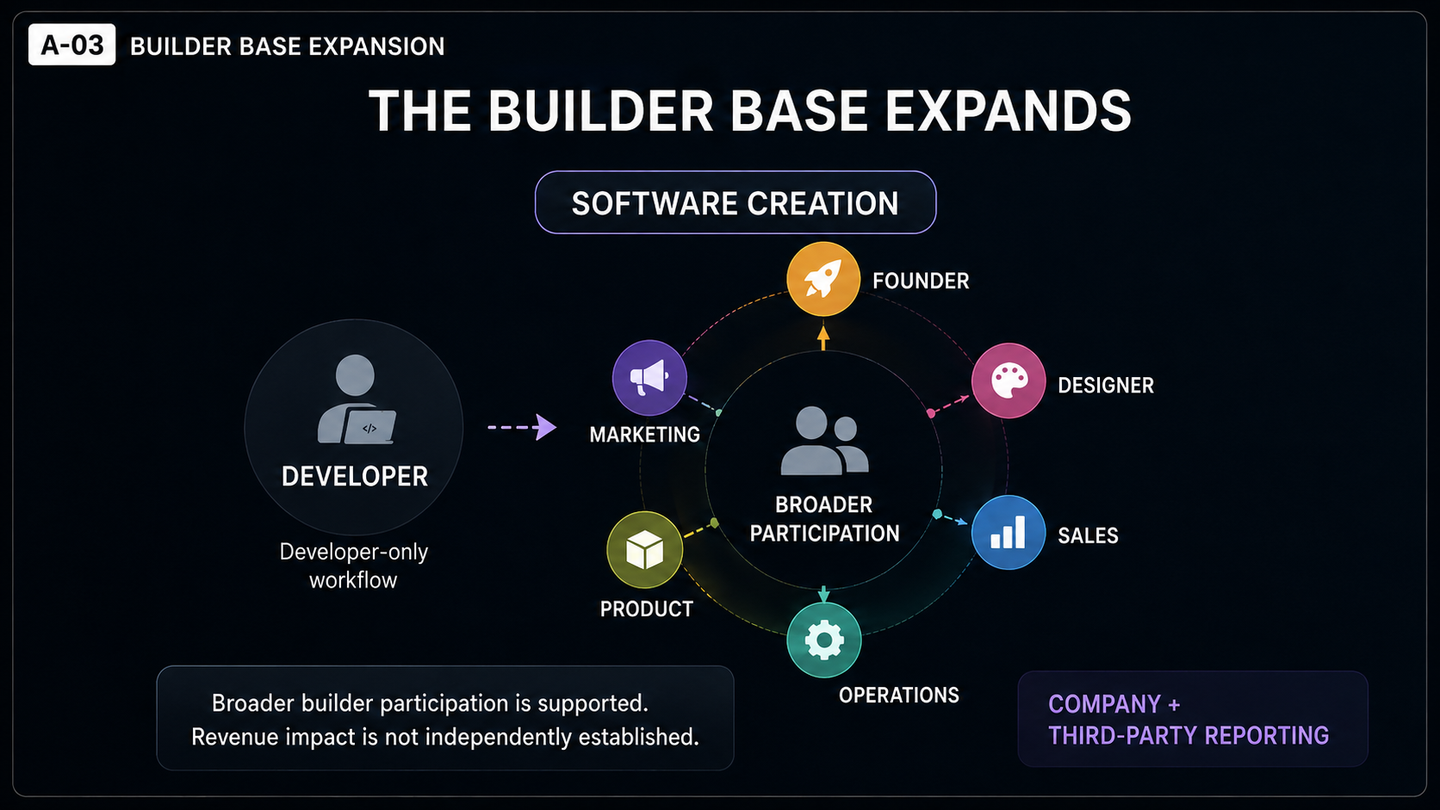
Anton Osika has repeatedly framed Lovable around the idea that software creation should not be limited to the small share of people who know how to code.
Third-party reporting later reflected that positioning in actual user descriptions.
Lovable said that many users were primarily non-technical, including founders, designers and salespeople.
The company also described people building more than simple marketing websites.
Reported examples included e-commerce sites, CRM systems, inventory tools, HR software and internal applications.
Those examples should not be treated as a complete census of Lovable’s customer base.
They do show that the company increasingly positioned itself beyond professional software engineering teams.
That broadening also appears in Lovable’s enterprise guidance, where product, operations, marketing and sales teams can create prototypes before handing code or systems to engineers.
That is a different proposition from replacing engineering.
It redistributes some of the earliest software-creation work.
7. RevenueLore Analysis – Lovable May Have Expanded the Creator Base
The distinction between accelerating developers and creating new builders may be one of the most important parts of the Lovable story.
A traditional developer tool sells into an existing professional workflow: the customer already knows how to create software, and the tool improves speed, convenience or quality. Lovable potentially changes the starting point. A founder with an idea, a salesperson who needs an internal tool or an operations employee who understands a workflow may be able to build a first version without waiting for a full engineering cycle.
That does not make those users software engineers. It means software creation can begin earlier and with fewer specialized skills. Commercially, that can expand the number of people who are able to initiate software projects.
The evidence supports the existence of a broader builder base. It does not establish that this expansion was the single cause of Lovable’s reported revenue growth; revenue, product expansion, market enthusiasm, distribution and enterprise adoption all moved during the same period. The safer interpretation is narrower: Lovable appears to have expanded who could participate in software creation.
8. But Building Software Is More Than Generating Code
Generating code is only part of building a usable application.
A real system often needs a database.
Users may need accounts and authentication.
Files need to be stored.
Applications may need APIs, payments, external services, AI models and deployment infrastructure.
After launch, somebody has to maintain those components.
This distinction matters because a code generator can produce impressive output while still leaving the user with significant technical work.
If that remaining work requires engineers, deployment expertise and multiple external services, the accessible market remains narrower than the interface initially suggests.
Lovable therefore had an incentive to absorb more of the application stack.
The more surrounding work the platform could handle, the closer the product could move from “AI that writes code” toward “software creation system.”
9. Lovable Expanded From Code Generation Toward an Application Platform
The product expanded in that direction.
Lovable supported integrations with tools such as Supabase and GitHub, giving users ways to connect generated applications to backend services and conventional development workflows.
Visual editing reduced the need to express every change through a prompt.
Agent capabilities pushed toward more autonomous implementation.
Lovable Cloud moved further still.
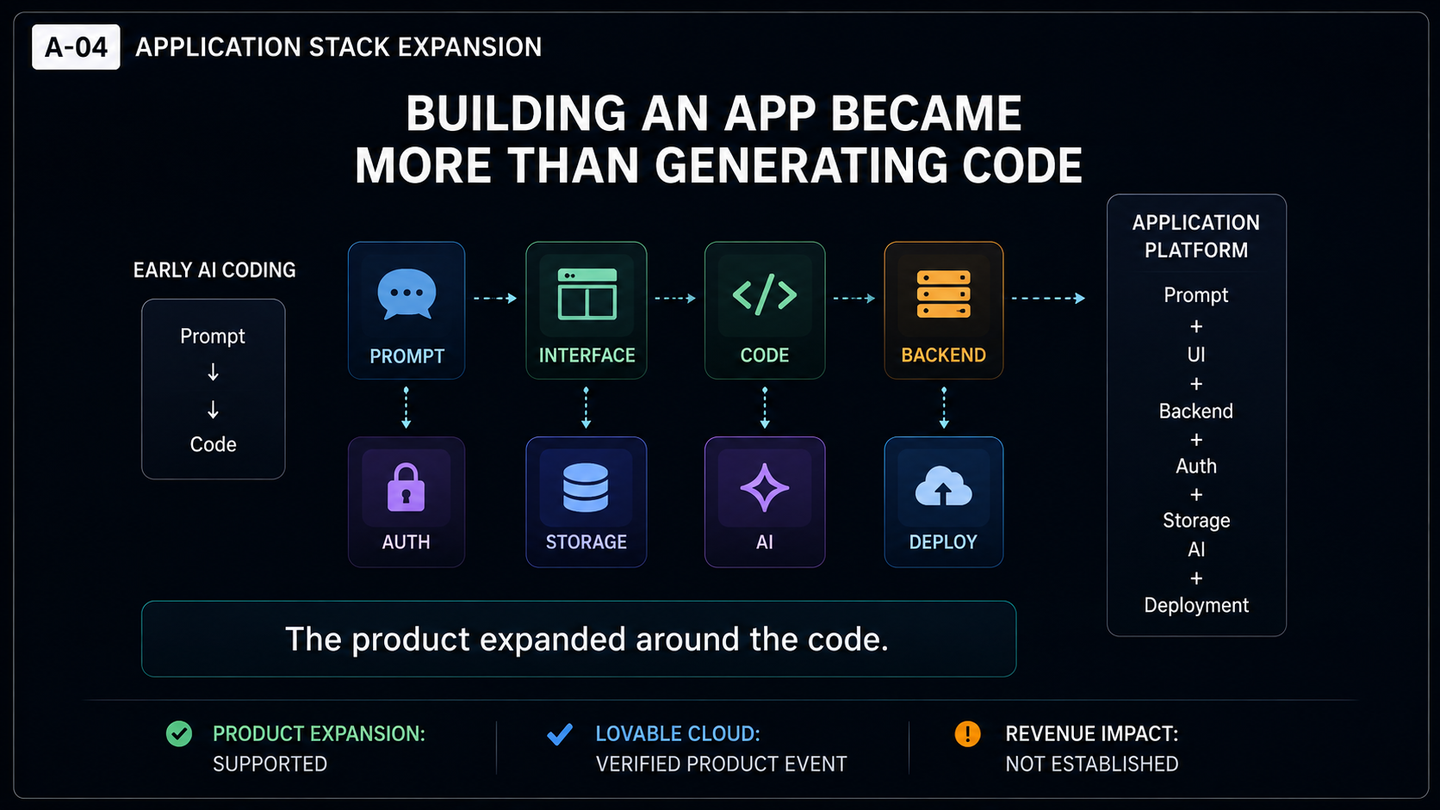
The company described the service as bringing database functionality, authentication, file storage, AI integration and other backend capabilities directly into the platform.
That changes what the user is buying.
The value proposition is no longer limited to:
describe an interface and receive code.
It moves toward:
describe an application and let the platform handle more of what is required to run it.
The distinction is commercially significant because each removed technical dependency lowers another barrier between an idea and a working product.
It also increases how much responsibility shifts onto Lovable itself.
10. RevenueLore Analysis – The Product May Be the Workflow Around the Model
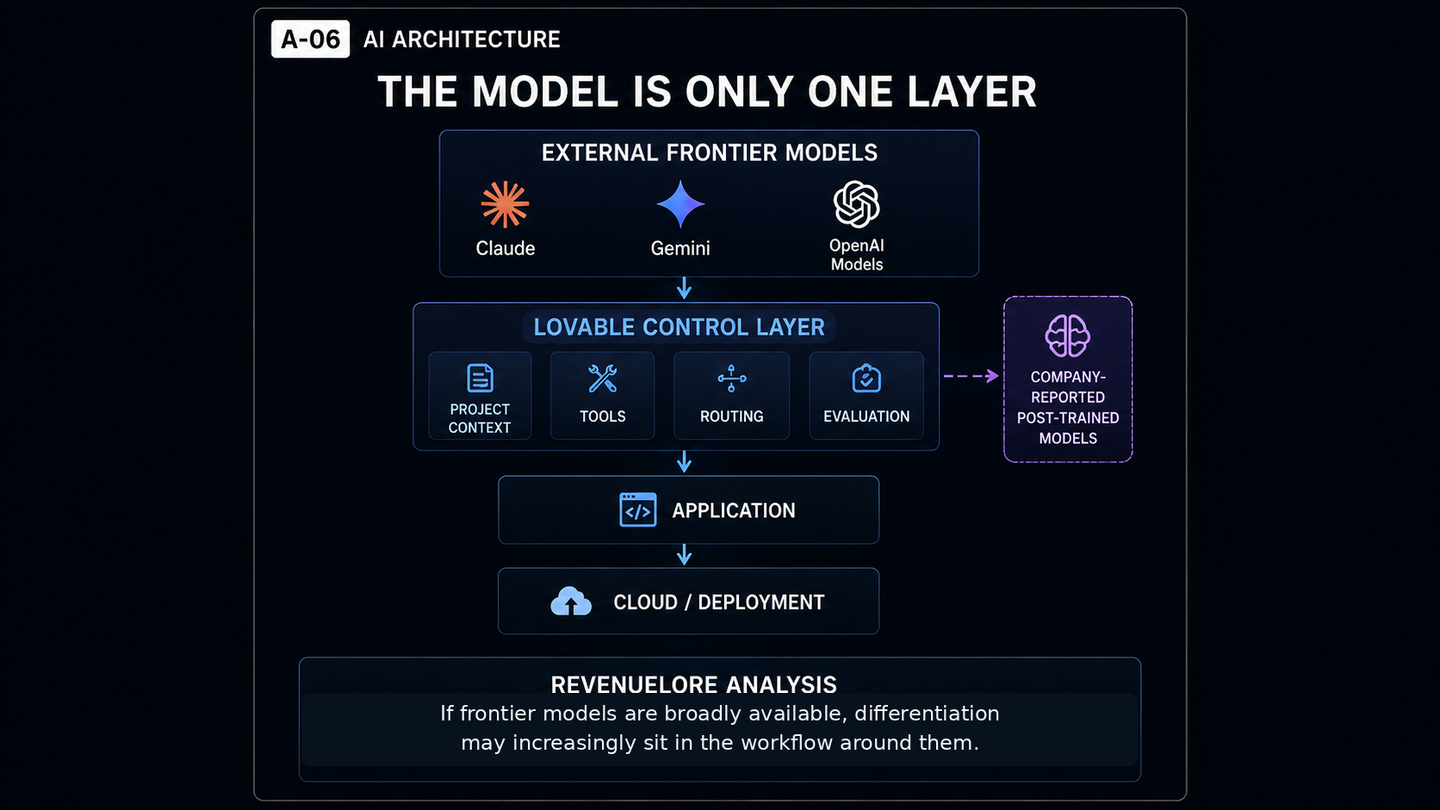
The most defensible long-term question about Lovable may not be whether its underlying AI model is better than every competing model.
Frontier models are available to many companies.
Lovable itself uses models from multiple external providers.
If those underlying capabilities become increasingly accessible, competitive value may move upward in the stack.
The product can differentiate through how it understands the project, routes tasks, preserves context, interacts with tools, edits files, connects infrastructure, evaluates outputs and turns generated code into a deployed application.
That does not prove Lovable has a durable moat.
It suggests a different place to look for one.
The value may increasingly sit in the control layer surrounding the models rather than in exclusive ownership of one model.
That becomes more plausible as the product absorbs more of the application workflow.
But it remains an analytical interpretation, not an independently verified statement about Lovable’s defensibility.
11. Lovable Uses External Models – and Also Says It Trains Its Own
Lovable is not a foundation-model company in the same sense as OpenAI, Anthropic or Google.
It relies on external frontier models.
The company has discussed using models from OpenAI, Anthropic and Google, while later reporting described a deeper infrastructure relationship with Google Cloud and access to Claude and Gemini.
That dependency does not reduce the product to a simple wrapper.
Lovable says it operates its own orchestration layer that decides which models, prompts, tools and context should be used for different tasks.
The company also says it has trained or post-trained internal models that handle some production workloads.
Both ideas can be true at once.
Lovable can depend significantly on external models while also developing proprietary systems around them.
The correct description sits between two common extremes.
Lovable is not merely a thin front end for one external model.
It also does not own every model in the stack.
12. The Business Appears to Combine Self-Serve and Enterprise Economics
Lovable’s commercial model has expanded alongside the product.
Earlier reporting described a subscription-driven business with self-serve users and larger plans.
The current pricing architecture is more usage-oriented.
Credits are used across building activity, cloud usage and AI functionality. Larger organizations can access Enterprise arrangements with volume-based structures.
That creates a hybrid commercial model.
A small user can begin with relatively little friction.
A larger organization can buy more capacity and enterprise functionality.
AI also introduces a different cost structure from traditional SaaS.
Generating code, running applications and invoking models can create usage-dependent infrastructure costs.
Credits provide one way to connect customer usage with those economics.
Public information does not establish exactly how Lovable’s revenue is divided among self-serve subscriptions, enterprise agreements, cloud usage and AI consumption.
The architecture itself is visible.
The revenue mix is not.
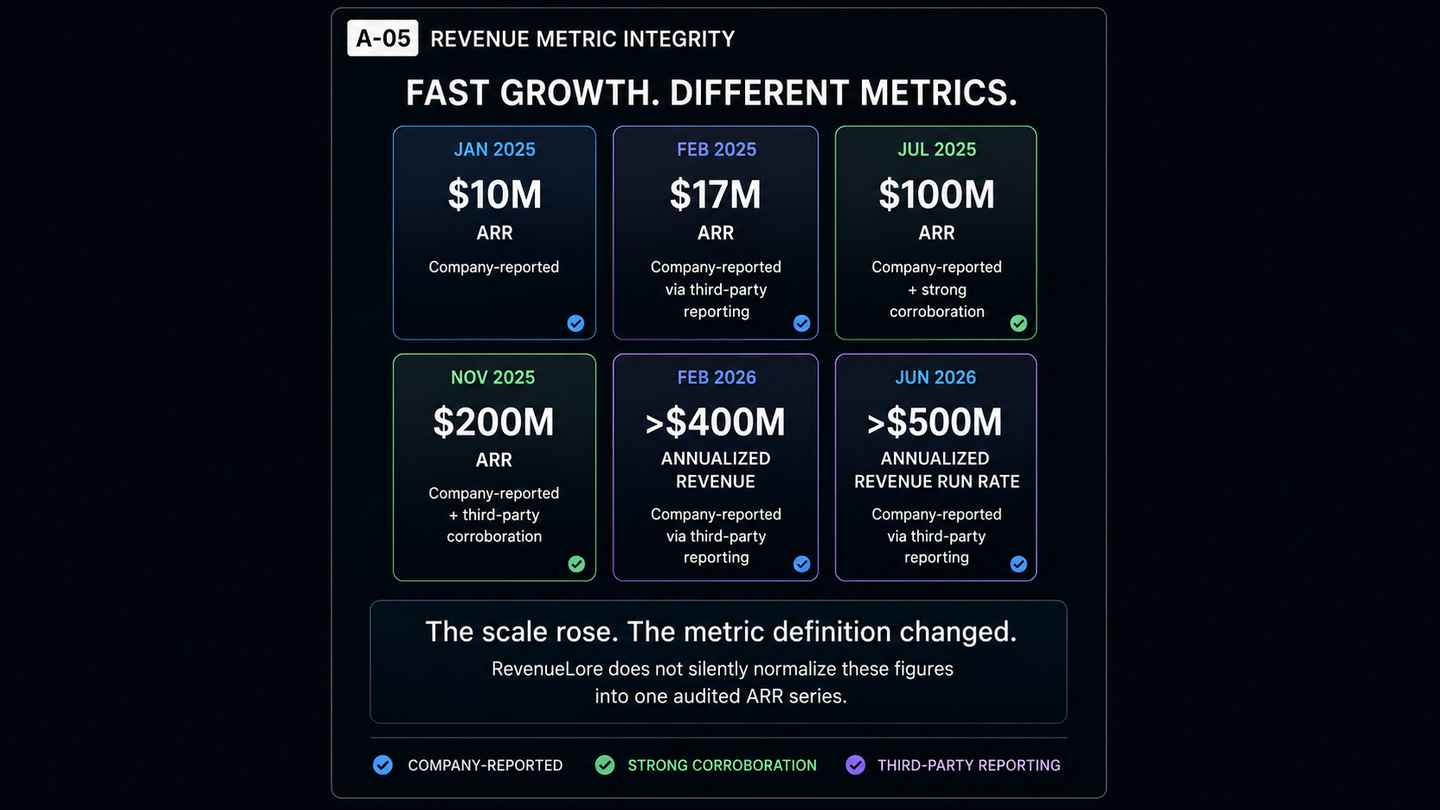
13. The Revenue Numbers Grew Fast – but the Metric Changed
Lovable’s reported financial progression is one of the reasons the company has attracted so much attention.
But the sequence needs to be read carefully.
| Date | Reported Metric | Evidence Status |
|---|---|---|
| Jan. 2025 | $10M ARR | Company-reported |
| Feb. 2025 | $17M ARR | Company-reported via TechCrunch |
| Jun. 2025 | ~ $75M ARR | Company-reported via third-party reporting |
| Jul. 2025 | $100M ARR | Company-reported + strong third-party corroboration |
| Nov. 2025 | $200M ARR | Company-reported + third-party corroboration |
| Feb. 2026 | More than $400M annualized revenue | Company-reported via third-party reporting |
| Jun. 2026 | More than $500M annualized revenue run rate | Company-reported via third-party reporting |
The first part of the series uses ARR.
The later figures use different language.
That distinction should not be erased for the sake of producing a cleaner growth chart.
Annual recurring revenue, annualized revenue and annualized revenue run rate can all describe business scale, but they do not necessarily follow identical definitions.
None of these private-company figures has been treated by RevenueLore as independently audited.
The trajectory is still notable.
The labels are part of the story.
14. The $500M Headline Needs the Right Label
The largest current headline requires the most care.
In June 2026, Lovable told TechCrunch that it had surpassed $500 million in annualized revenue run rate.
That is the source language RevenueLore should preserve.
It should not silently become:
$500 million ARR.
It should not become:
$500 million of recognized annual accounting revenue.
And it should not become:
$500 million in profit.
A run-rate figure annualizes the current pace of business.
That can be useful for understanding momentum.
It is not the same thing as an audited historical income statement.
The distinction is especially important in a company growing as rapidly as Lovable, where the current monthly or quarterly revenue base may be materially different from the earlier part of the year.
The headline is still substantial.
It simply needs the correct label.
15. Projects and Visitors Are Scale Signals – Not Customer Counts
Lovable has also reported extraordinary product activity.
By June 2026, the company said more than 50 million projects had been created and that roughly one million new projects were being generated each week.
By August, reporting referred to approximately 60 million projects and roughly 900 million monthly visitors to projects hosted through Lovable.
Those figures indicate substantial reported activity around the platform.
They should not be translated into customer counts.
One user can create multiple projects.
A project can be experimental, abandoned, private, duplicated or never deployed.
A public application can receive visitors without the visitors themselves becoming Lovable customers.
Traffic to a Lovable-built application is not the same metric as usage of Lovable’s builder product.
The same discipline applies to the number of projects.
Projects created tell us something about creation activity.
They do not tell us how many applications remain active, how many generate revenue, how many are maintained or how many represent durable businesses.
Scale is visible.
Durability is a separate question.
16. Funding and Valuation Tell a Different Story
Lovable’s financing history grew rapidly as well.
In July 2025, the company raised a $200 million Series A at a $1.8 billion valuation.
In December, it announced a $330 million Series B at a $6.6 billion valuation.
In August 2026, Lovable raised another $400 million in Series C funding at a $13.3 billion valuation.
Those numbers describe investor capital and investor expectations.
They do not describe customer revenue.
A funding round gives the company money to operate and expand.
A valuation reflects the price investors are willing to assign to the business under the financing terms.
Neither is interchangeable with sales.
A $13.3 billion valuation does not mean Lovable generates $13.3 billion in revenue.
Nor does raising hundreds of millions of dollars establish profitability.
The financing story belongs beside the revenue story.
It should not be merged with it.
17. Could Lovable Change the Buy-vs-Build Decision?
One of the more ambitious implications of AI software creation is not about developer productivity at all.
It concerns the traditional decision between buying software and building it internally.
Historically, buying an existing SaaS product is often attractive because custom software is expensive.
A company may prefer to pay for a standardized CRM, workflow tool or internal platform rather than hire developers to build and maintain its own version.
If software creation becomes dramatically cheaper, that calculation can change.
Lovable has highlighted customer examples in which employees created internal tools and organizations considered replacing certain existing SaaS subscriptions.
The Nursa case is one example.
That is interesting evidence.
It is not proof that SaaS as a category is being replaced.
A custom internal system can be inexpensive to create and still become expensive to maintain.
Commercial SaaS also includes ongoing support, upgrades, integrations, reliability, compliance and security work that may not be obvious at the moment a replacement prototype is built.
The more defensible question is therefore narrower:
Does lower software-creation cost move the point at which some organizations choose to build instead of buy?
Lovable provides evidence that the question is becoming more relevant.
It does not yet provide a general answer.
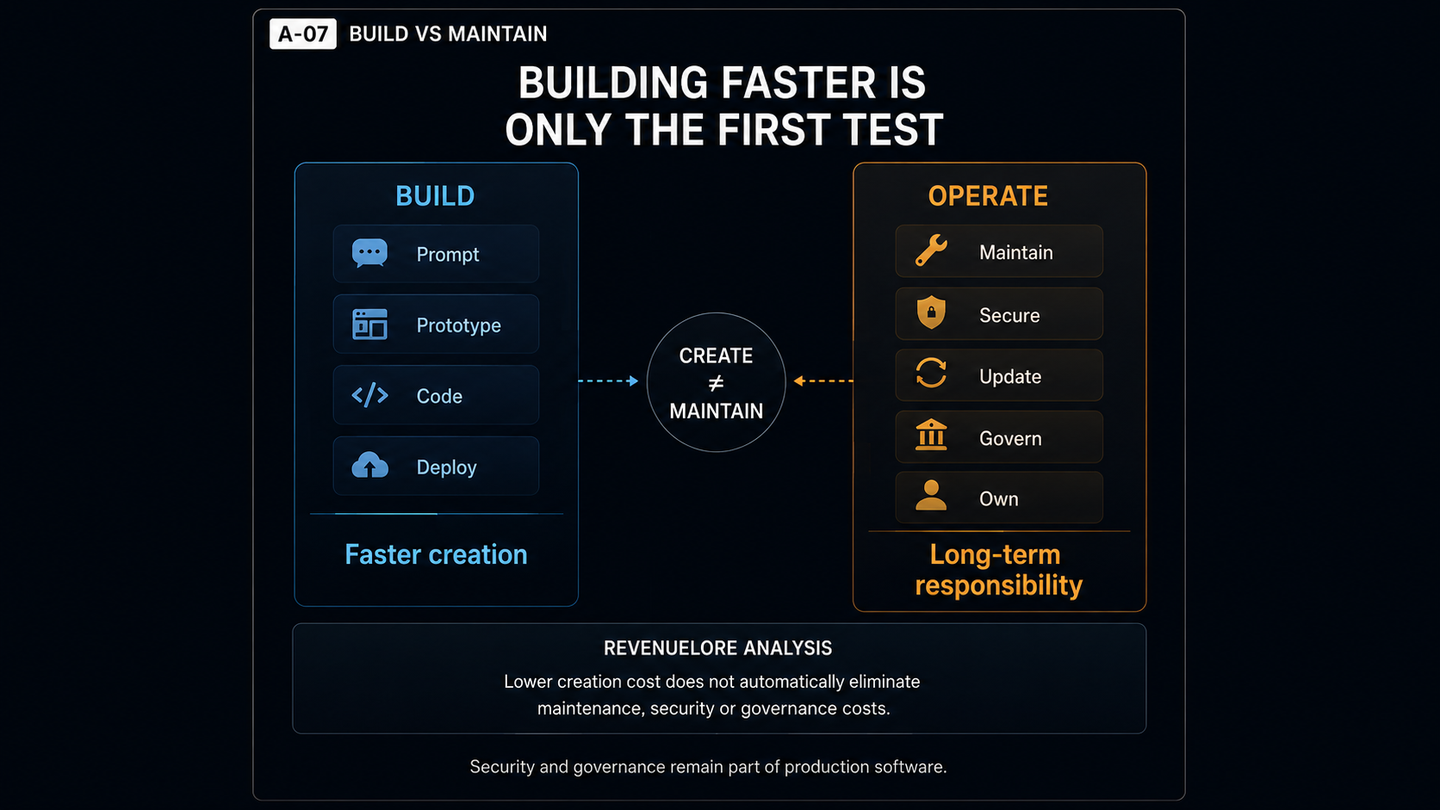
18. The Harder Test Begins After the App Is Built
Vibe coding has a natural bias toward the moment of creation. A prompt is entered. An interface appears. Features begin working. The result can feel dramatically faster than conventional development.
But software continues changing after launch. Dependencies receive updates. APIs change. Browsers change. Security vulnerabilities appear. Databases grow. Users behave in unexpected ways. Infrastructure fails. A system that worked when it was created may require substantial maintenance six months or three years later.
This is where the long-term economics of AI-generated applications become less certain. Lovable has strong evidence of rapid creation activity. Public evidence is much weaker on the proportion of those projects that remain maintained production systems over long periods. That is not a unique failure of Lovable. It is a broader unresolved question for AI-generated software. Creation cost can fall dramatically while ownership cost remains significant.
19. Security and Governance Become More Important as Building Gets Easier
Making software creation available to more people creates another consequence: more creators can mean more systems that need to be secured and governed. Lovable’s own enterprise material reflects this tension. The company describes workflows in which non-technical teams can prototype while engineering teams maintain review and production ownership. That model recognizes something important: software creation can be democratized without eliminating the need for technical controls.
Lovable also disclosed a security incident in 2026 involving public projects, where authenticated users with a project link could potentially access project information that should not have been exposed in that way. The company said it fixed the issue and changed parts of its response process. One incident does not prove that Lovable or vibe coding is inherently insecure. It does show why security becomes part of the product as the platform moves from experimentation toward production use.
The easier software becomes to create, the more important it can become to decide who can create it, who can access it and who remains responsible after deployment.
20. RevenueLore Analysis – What Actually Changed?
Lovable’s development can be understood as a sequence of expanding boundaries. First, AI reduced some of the effort required to write code. Then the interface changed. Natural language let users express intent without manually implementing every technical detail. That widened participation. Founders, designers, salespeople and other non-specialists could begin building software rather than merely describing what they wanted engineers to build.
The product boundary expanded too. Backend services, authentication, storage, cloud infrastructure, AI integrations and deployment moved closer to the same workflow. The commercial model expanded alongside it. Self-serve usage could coexist with enterprise purchasing and usage-sensitive credits. As more people and organizations built software, governance and maintenance became more important rather than less.
Those changes help explain why Lovable should not be understood only as a code generator. The product increasingly sits between an idea and a working application. Public evidence supports that transformation. It does not establish which part of the transformation produced the company’s reported revenue scale. Open-source distribution, product design, the broader AI boom, external model improvements, enterprise adoption, cloud infrastructure, pricing and market timing all developed together. The transformation is observable. The causal weights are not.
What Founders Should Not Learn From Lovable
Lovable is an unusually fast-growing company.
That makes it especially easy to extract the wrong lessons.
The first is that an open-source project only needs to go viral before a large business appears automatically.
Lovable’s own history contradicts that simplification. The company describes two early commercial launches that failed to gain meaningful traction before later iterations worked better.
Another bad lesson is that one distribution channel creates product-market fit.
Product Hunt, Hacker News, social media, community and partnerships all appeared in the company’s early distribution story.
None is independently established as the single cause of growth.
The case also does not show that developers are becoming unnecessary.
Lovable’s own enterprise workflows preserve a role for engineering review and ownership.
Nor does the case establish that custom AI-built applications will replace SaaS generally.
Building software and operating software are different economic problems.
Finally, Lovable’s dependence on external frontier models does not make the company automatically defenseless, just as proprietary models do not automatically create a moat.
The useful lesson is not that one tactic produced an extraordinary outcome.
It is that product boundaries, user boundaries and commercial boundaries all changed together.
What Can We Actually Learn?
Lovable offers several more defensible lessons.
Interfaces can create new users
A product can expand a market by lowering the skill threshold required to participate in a workflow.
The value does not have to come only from making experts faster.
Generated output may not be the whole product
Code generation attracts attention, but applications require much more than code.
Reducing friction across backend services, deployment and infrastructure can be commercially important.
Product and distribution can evolve together
Lovable’s early history does not support a single growth-hack explanation.
Commercial traction emerged while the product, positioning, integrations and distribution strategy were all changing.
AI application companies can create value without owning every model
External models can provide underlying intelligence while the application company owns context, orchestration, workflow, tooling and customer experience.
That does not guarantee defensibility, but it creates a meaningful product layer.
Lower creation cost can change the buy-versus-build calculation
Some software that was previously uneconomical to build internally may become more feasible.
That does not eliminate the long-term maintenance costs of custom systems.
More creators can increase governance requirements
Making software creation easier does not make security, engineering ownership or access control less important.
It can make them more important.
Verification Notes
RevenueLore separates observable product and financing events from company financial claims, founder interpretations, third-party reporting and editorial analysis.
VERIFIED / CONTEMPORARY FACTS
Lovable was founded by Anton Osika and Fabian Hedin.
The company’s history traces its origins to the open-source gpt-engineer project in 2023 and a later commercial web product.
Lovable publicly launched in November 2024.
Contemporary third-party reporting documented early Product Hunt and Hacker News exposure.
Lovable’s major financing rounds include:
- $200 million Series A at a $1.8 billion valuation in July 2025,
- $330 million Series B at a $6.6 billion valuation in December 2025,
- and $400 million Series C at a $13.3 billion valuation in August 2026.
Lovable Cloud expanded the company’s product into backend infrastructure, authentication, storage and other application services.
Lovable also publicly disclosed and responded to a security incident involving public-project access in 2026.
COMPANY-REPORTED
Most of Lovable’s revenue and scale metrics are private-company claims.
These include:
- $10 million ARR in early 2025,
- $17 million ARR in February 2025,
- $100 million ARR in July 2025,
- $200 million ARR in November 2025,
- more than $400 million in annualized revenue in early 2026,
- and more than $500 million in annualized revenue run rate in June 2026.
Project, visitor and Fortune 500 usage figures are also primarily company-reported.
RevenueLore does not treat those metrics as independently audited unless such verification is explicitly available.
FOUNDER-REPORTED
Anton Osika has repeatedly framed Lovable’s mission around expanding software creation beyond people who already know how to code.
Founder and company retrospectives also describe:
- early commercialization attempts,
- how users perceived the product,
- changes to positioning and distribution,
- and the intended importance of non-technical builders.
These accounts provide valuable context but should not be treated as independent proof of causality.
STRONG THIRD-PARTY CORROBORATION
TechCrunch contemporaneously reported several of Lovable’s major financial milestones, including the company’s:
- $100 million ARR claim,
- $200 million ARR claim,
- and later $500 million annualized revenue run-rate claim.
RevenueLore treats that reporting as meaningful third-party corroboration.
It does not convert private-company claims into independently audited financial results.
CORROBORATION is not AUDIT.
REQUIRES CONTEXT
Lovable’s first two commercial launches can be described as failed launches because that is the company’s own retrospective language.
That does not mean the underlying technology failed.
Open-source attention should not be treated as paying demand.
ARR, annualized revenue and annualized revenue run rate should not be silently normalized into one metric.
Projects should not be treated as customers, active production applications or businesses.
Visitors to applications built with Lovable are not the same metric as users or customers of Lovable itself.
Fortune 500 usage does not establish company-wide enterprise deployment.
Customer stories such as Nursa provide examples of buy-versus-build behavior but do not establish that SaaS is broadly being replaced.
Current pricing and credit structures should not be projected backward as historical pricing.
The April 2026 security incident provides relevant governance context but does not establish that all Lovable-built or vibe-coded software is insecure.
REVENUELORE ANALYSIS
RevenueLore’s analysis is that Lovable may have expanded the effective creator base for software by reducing how much technical expertise is required to initiate application development.
A second interpretation is that Lovable’s product value increasingly resides in the workflow surrounding code generation: project context, integrations, backend services, deployment, model orchestration and enterprise controls.
RevenueLore also sees a credible possibility that lower software-creation costs could alter the traditional buy-versus-build threshold for some internal applications.
None of those interpretations proves that Lovable will broadly replace traditional SaaS or professional software engineering.
Finally, the long-term economic test may shift from creation to ownership.
A system that is easy to generate still has to remain secure, maintainable and governed over time.
These are editorial interpretations rather than independently established causal findings.
RevenueLore Takeaway
Lovable’s biggest commercial idea may not be that AI can write code. That capability is increasingly available across the industry. The more consequential shift may be the amount of specialized work that can be removed between an idea and usable software.
Lovable began with an open-source coding experiment. The commercial product lowered the interface barrier through natural language, and the potential builder base widened beyond professional developers. Then the product itself expanded into editing, integrations, backend infrastructure, deployment, AI services and enterprise workflows. The company’s reported financial growth followed at extraordinary speed, reaching $100 million ARR in July 2025, $200 million ARR in November and, by June 2026, a company-reported annualized revenue run rate above $500 million. Those numbers remain private-company claims, and the later metric should not be silently relabeled as ARR.
The more durable lesson sits underneath them. The larger opportunity may be reducing how much specialized work stands between an idea and usable software. But lowering the cost of creation does not automatically lower every other cost. Software still needs to be maintained, secured and governed.
Lovable’s next test is therefore different from its first one: not whether more people can build software, but whether software built by more people can remain reliable enough to operate over time.
Sources
- Lovable – GPT Engineer and Lovable: The Evolution
- Lovable – Lovable's Two Failed Launches and What We Got Wrong About PLG
- Lovable – Zero to $10M ARR in 2 Months
- TechCrunch – Sweden's Lovable, an App-Building AI Platform, Raises Funding After Rapid Growth
- Lovable – $200M Series A / $1.8B Valuation
- Lovable – $100M ARR & Lovable Agent
- TechCrunch – Lovable Crosses the $100M ARR Milestone
- Lovable – One Year of Lovable
- Lovable – Introducing Lovable Cloud and AI
- TechCrunch – Lovable Raises $330M at a $6.6B Valuation
- TechCrunch – Lovable Signs Multiyear Google Cloud Deal
- TechCrunch – Lovable Says It Hit a $500M Annualized Revenue Run Rate
- Lovable – The Model Picker Is a Dead End
- Lovable – Response to the April 2026 Incident
- TechCrunch – Lovable Confirms $13.3B Valuation and $400M Series C